

Why digital health is about to enter a “scale game,” leading to more mergers

This is a co-written piece with 7wireVentures’s Alyssa Jaffee
The pandemic was a boom time for digital health. It created massive tailwinds as regulatory barriers were broken down, leading to more innovation than ever before. As the demand for virtual care skyrocketed, entrepreneurs were able to build virtual care companies without needing a physical location present in all 50 states. Enthusiasm for the sector amongst VCs also shot up in the wake a string of impressive exits: Livongo sold to Teladoc for $18.5 billion, and PillPack/ One Medical were acquired by Amazon for around $750 million / $2 billion respectively. Venture capital funding ballooned to more than $29 billion in 2021.
That hype period may have led to many positive developments for the sector, but also some new frictions. Money was flowing out the door so quickly that venture rounds were finalized without much diligence. We saw founders taking millions of dollars off the table in secondaries, and we saw news headline after headline announcing new rounds of capital sometimes a few months after the prior round had closed.
Somehow, amidst all the frenzy, the fundamental first rule of startups was forgotten: Focus on building a great company before all else. VCs investing at the time often found themselves looking at companies that Alyssa likes to call having more “sizzle than steak,” meaning the story was there but not the execution nor the operational excellence.
In the past few years, the market has changed, and there’s no denying it. Good companies are still raising capital, and we’ve seen more examples of that in the past few months. But investors are now far more disciplined on valuations (outside of AI), and on how much they invest. They want to see companies hitting their milestones and finding product/market fit. Because of this, we expect to see companies that struggle to prove a business model finding alternative exit paths or quietly shutting down in 2024 and 2025.
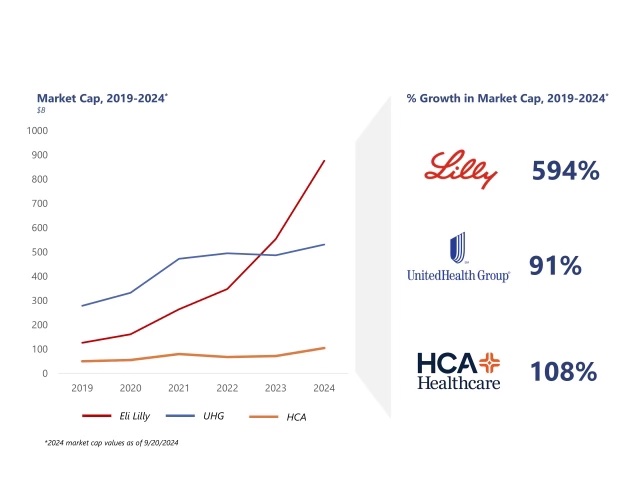
But here’s another trend that hasn’t gotten nearly so much attention. In the time frame that digital health has gone through its own hype cycle – both a boom and a bust – many of health care’s largest incumbents have been on a tear. In the 2020 to 2023 timeframe, as many publicly-traded digital health companies flatlined and struggled, companies like Eli Lily, United HealthGroup (UHG) and HCA continued to grow. To provide a specific example, UHG’s revenue in 2019 was $242 billion, and its market cap was $278 billion. By 2023, its revenue was up $372 billion for the year and its market cap shot up to $487 billion. By the time you’re reading this post, the company’s market cap has hit more than $531 billion!
Meanwhile, UHG’s Optum, announced revenue in 2019 of $113 billion. By 2023, its revenue was up to $227 billion.
So what does this mean for disruptors? Should they simply give up and let the big guys grow even larger?
Well, we’d argue no. But the game does need to be played differently. And to better understand that, we need to take a closer look at an acquisition that occurred in 2020 without a lot of fanfare. That acquisition truly benefited digital health as a sector, but we’d argue it would not have happened in 2024.
In 2024, the rules have been rewritten. So let’s take a walk down memory lane to understand what happened, what we can learn from it, and what’s changed in the years since.
Changing the playbook
Let’s take a look at a deal from four years ago: The $470 million buy-up of AbleTo by Optum.
Optum, which is a unit of UnitedHealth Group (UGH), acquired AbleTo to beef up its virtual behavioral health footprint. At the time, one would have to conservatively estimate that AbleTo was netting somewhere around $50 million in revenue and showing strong momentum. Those numbers were never publicly disclosed, so we can’t know for sure, although we have a hunch that this is about correct.
`Upcoming Sessions
Live conversations with the people shaping healthcare.

Office Hours
A live Q&A with Christina Farr and Ruth Reader, exclusively for Second Opinion Premium members. Thursday, December 3, 3–4 p.m. ET / noon–1 p.m. PT.

AMA with Doximity CEO Jeff Tangney
Join Doximity CEO Jeff Tangney for a live Q&A on where clinicians are finding value with AI, how Doximity has evolved, and building a company from zero to IPO.

The Shift Left & the Impact of the Midterms on Healthcare
Democrats just took both chambers. Aneesh Chopra, Christopher Kerns and Mike Desjadon join Ruth Reader and Christina Farr live to talk through what they'll try to do on healthcare — and what's actually achievable under a Republican White House.

Is It Finally the Moment for Alternative Health Plans?
Register Here Employers are under growing pressure to control healthcare costs while improving access, outcomes, and the member experience. That has renewed

Type 2 Diabetes & Cardiometabolic Care: Wearables, AI & GLP-1s
Register Here The rise of wearables, GLP-1s, and AI is reshaping treatment for Type 2 diabetes, weight loss, and metabolic disease.

Verifying AI in Medicine: Is Healthcare AI Actually Ready for Deployment?
Is AI ready for real-world clinical care? Dr. Zak Kohane and Protege’s Engy Ziedan debate what it takes to safely trust AI in diagnosis and treatment, from benchmark performance and clinical evidence to whether we’re holding AI to a higher standard than humans.

Why Are Hospitals Hiring Chief AI Officers?
As AI moves from pilots into day-to-day healthcare operations, health systems are having to decide who should actually own the


Where are AI Agents Actually Working in Healthcare, and Why?
While the healthcare industry remains locked in a high-level debate over the theoretical potential of artificial intelligence, a select group of

Top Employers Share What Healthcare Startups Need to Know in 2026
As enterprise health purchasers face volatile medical cost trends and tightening operational margins, the standard vendor pitch of "improved clinical efficiency&